Daily vs Monthly Gold Loan Schemes: How They Affect Interest and Revenue
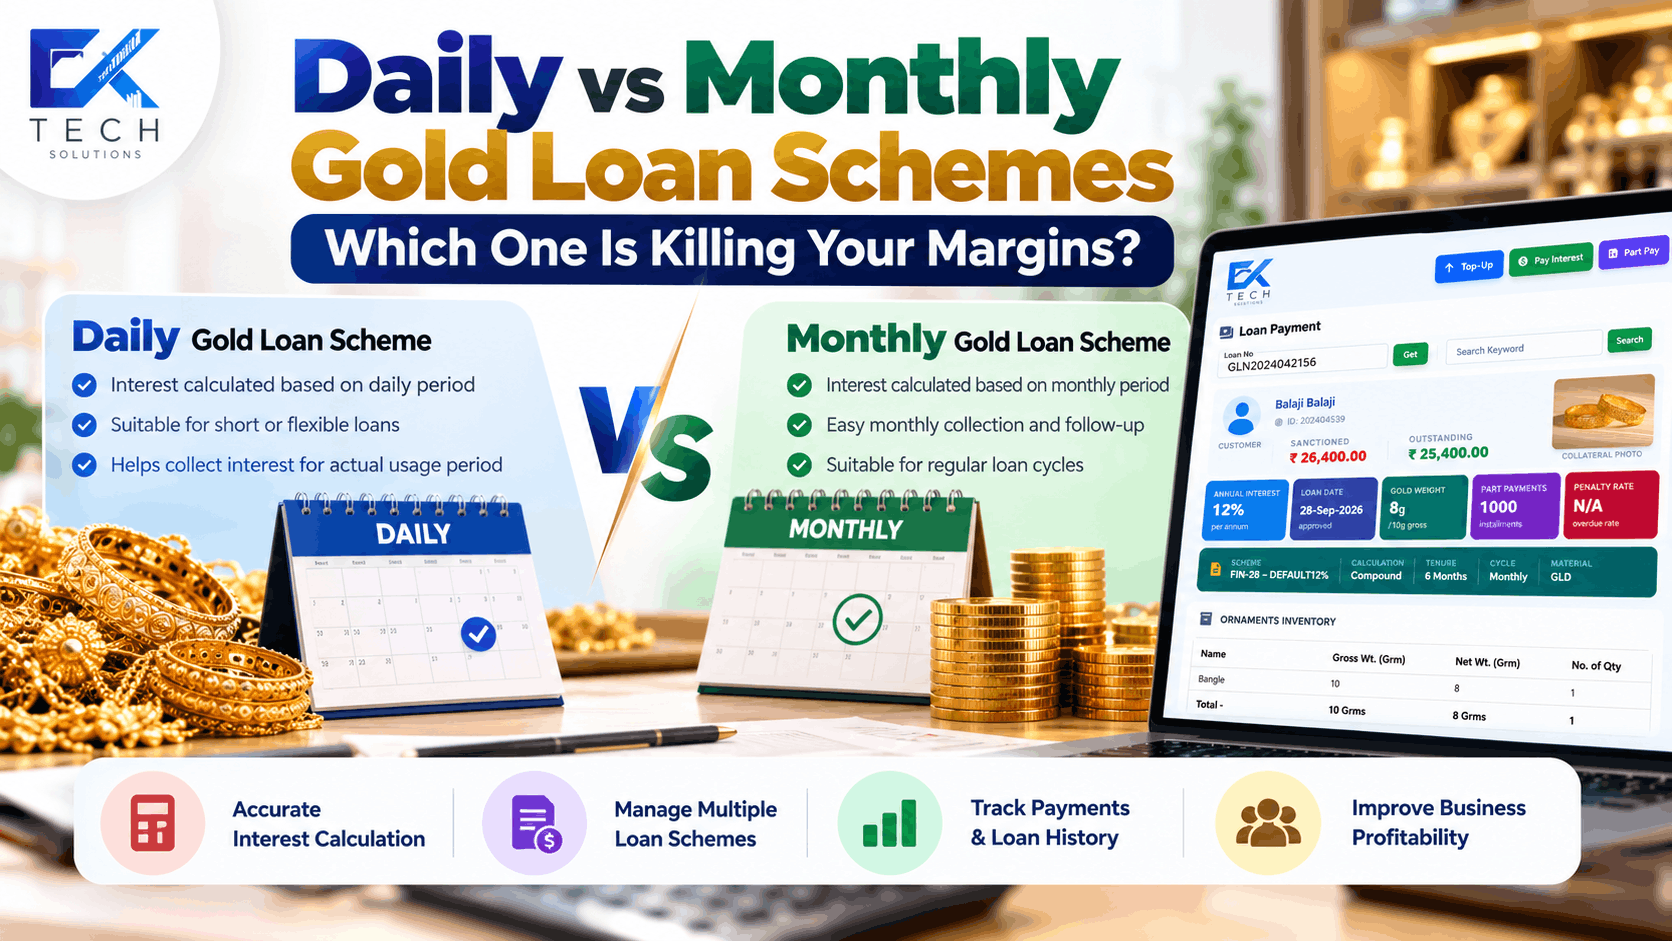
Daily vs Monthly Gold Loan Schemes: Which One Is Killing Your Margins?
Understand the difference between daily and monthly gold loan schemes, interest calculation, and how software can help manage loan schemes.
Daily vs Monthly Gold Loan Schemes
Gold loan businesses may use different interest schemes based on their business model and customer requirements. Two common approaches are daily and monthly gold loan schemes.
A daily scheme calculates interest based on the applicable number of days, while a monthly scheme works around monthly periods and configured business rules.
However, one scheme is not automatically more profitable than the other. The actual result depends on the interest rate, calculation method, loan tenure, payment behavior, and operating costs.
Daily vs Monthly Gold Loan Interest
| Factor | Daily Scheme | Monthly Scheme |
|---|---|---|
| Calculation Period | Based on applicable days | Based on applicable months |
| Suitable For | Flexible or shorter periods | Regular monthly cycles |
| Follow-Up | Based on applicable dates | Often aligned with monthly dates |
| Margin Impact | Depends on business rules | Depends on business rules |
Common Problems with Manual Interest Calculation
Many gold loan businesses manage different schemes using calculators, Excel sheets, registers, or separate interest tables.
Staff may need to manually check:
When the number of active loans increases, repetitive calculations can become time-consuming and may lead to data entry or calculation errors.
Why Gold Loan Interest Calculation Matters
A small difference in scheme configuration can affect interest collection across many loans. Businesses should therefore review factors such as:
Interest Rate
The rate configured for the loan scheme.
Calculation Method
How interest is applied to the loan.
Loan Tenure
The period for which the loan remains active.
Payment Behavior
Early payments and longer loan periods can affect results.
Collection Costs
Staff time and follow-up costs also matter.
Scheme Usage
Actual customer usage can affect business performance.
CK Tech Solutions Gold Loan Scheme Management
CK Tech Solutions Pawn Broking Software – FinApp can help businesses manage loan schemes and related calculation settings in one system.
Interest Rate
Maintain the configured interest rate.
Loan Scheme
Associate the applicable scheme with the loan.
Calculation Method
Maintain the configured calculation method.
Tenure & Cycle
Manage applicable loan tenure and interest cycle.
How CK Tech Solutions FinApp Works
1. Configure the Scheme
Set the applicable interest rate, calculation method, tenure, and interest cycle.
2. Create the Loan
Create the customer loan and select the appropriate scheme.
3. Calculate Interest
Configured calculation rules can reduce repetitive manual interest calculations.
4. Track Payments
Maintain payment information and review loan status and outstanding amounts.
Benefits of Gold Loan Software
Reduce Manual Calculations
Use configured rules instead of repeatedly calculating interest manually.
Manage Multiple Schemes
Keep different loan schemes organized in one system.
Reduce Data Entry Errors
Keep loan and scheme information together.
Track Active Loans
Monitor loans and their current status more easily.
Improve Payment Tracking
Maintain payment information and loan history.
Review Scheme Performance
Use loan and payment information to understand scheme usage.
Frequently Asked Questions
Conclusion
Daily and monthly gold loan schemes can produce different results depending on interest rates, calculation methods, loan tenure, payment cycles, and customer behavior.
Instead of assuming that one scheme is always better, businesses can review their actual loan and payment data.
CK Tech Solutions Pawn Broking Software – FinApp can help businesses manage loan schemes, interest settings, loan information, and payment records in a structured system.
Related Articles
You Might Also Like
Collateral Loan Management: A Simple Guide for Businesses
Top Challenges Facing Gold Finance Businesses in South India
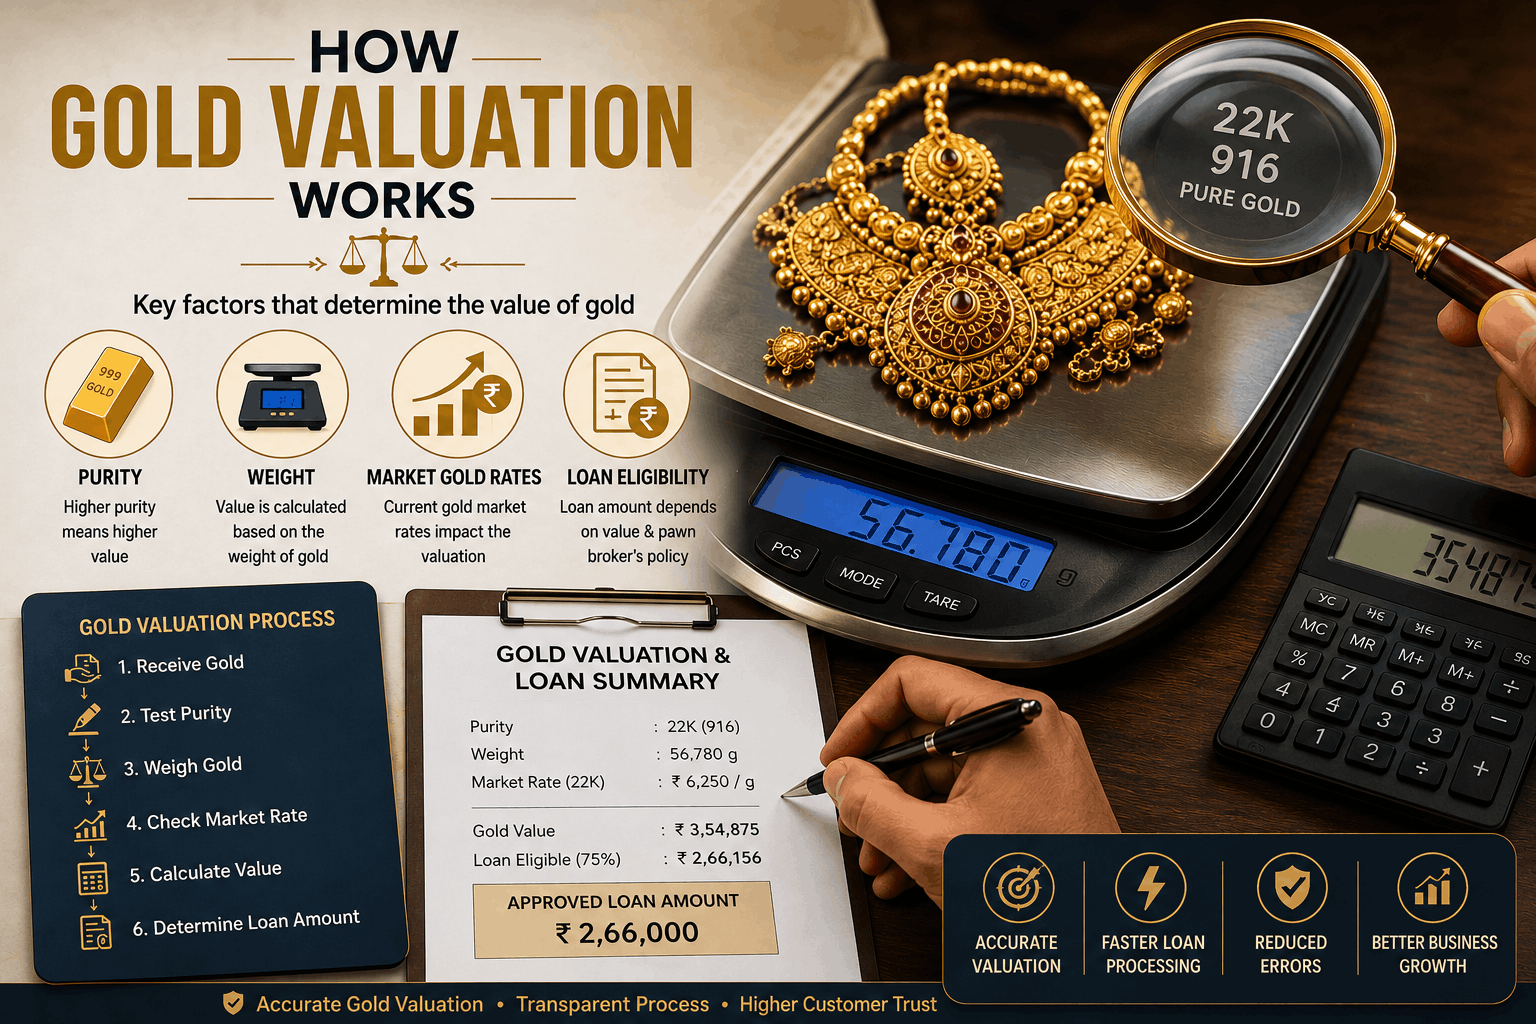
How Gold Valuation Works: Complete Guide for Gold Loans and Pawnbrokers
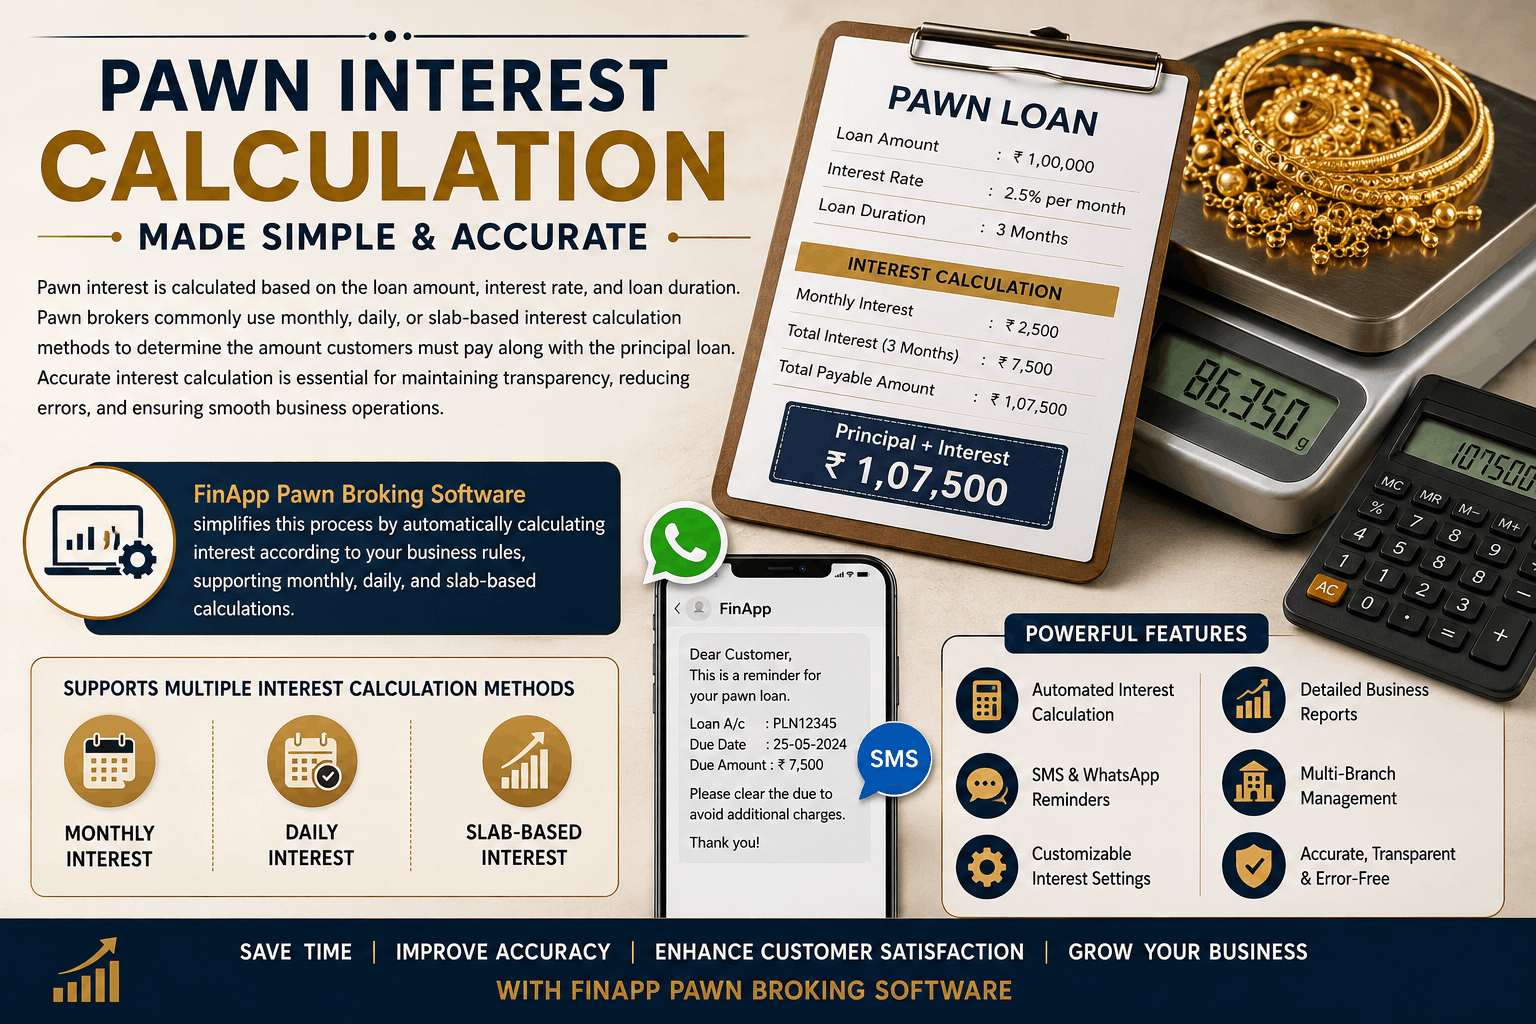
Pawn Loan Interest Explained: Step-by-Step Calculation Guide